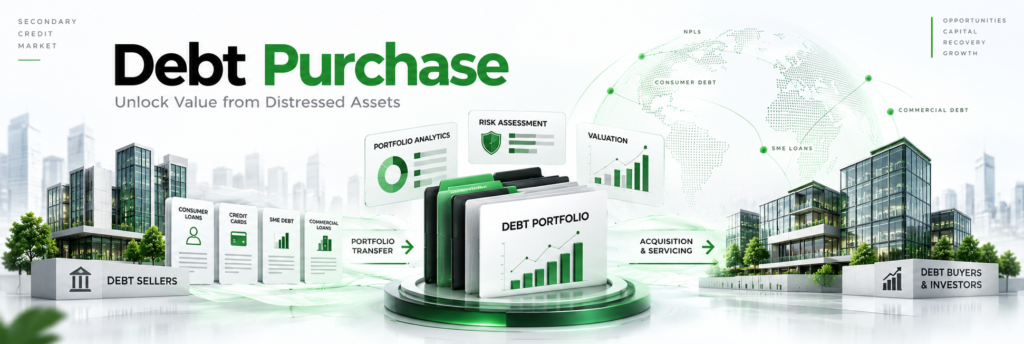
The debt purchase market is a secondary market in which outstanding receivables, distressed debt, non-performing loans, and other credit exposures are transferred between creditors, debt buyers, investors, and specialist financial institutions. It provides a mechanism for lenders and other debt owners to dispose of selected portfolios while allowing specialist buyers to acquire assets based on their expected recovery potential.
Debt purchase can cover a wide range of asset classes, including consumer loans, credit cards, personal loans, commercial receivables, SME debt, mortgages, vehicle finance, non-performing loans, and other secured or unsecured obligations.
A debt purchase transaction is not simply the transfer of an outstanding balance. Buyers need to understand the composition, quality, documentation, legal position, historical performance, recovery potential, servicing requirements, and costs associated with the portfolio. Sellers need to prepare reliable data, establish the transaction scope, and provide sufficient information for prospective buyers to conduct due diligence.
The value of a debt portfolio is therefore influenced by the relationship between its outstanding balance and the cash flows that can realistically be recovered. Purchase price, recovery timing, servicing costs, legal considerations, portfolio risk, and market conditions all contribute to the economics of a transaction.
This guide provides a comprehensive overview of debt purchase, covering the market structure, portfolio types, transaction process, valuation, due diligence, buying and selling considerations, servicing, technology, risks, and key market terminology.
What Is Debt Purchase?
Debt purchase is the acquisition of debt or the relevant legal, contractual, or economic interest in a portfolio of receivables from an existing creditor or debt owner.
When a lender originates credit, the resulting receivable represents an expected future cash flow. If accounts become delinquent, distressed, or otherwise meet the seller’s criteria for disposal, the creditor may decide to retain the portfolio, restructure the accounts, outsource servicing, or sell the debt.
A debt purchaser evaluates the portfolio and determines an acquisition price based on expected future recoveries and associated risks.
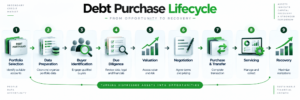
A simplified debt purchase lifecycle is:
Debt Origination → Portfolio Selection → Data Preparation → Buyer Due Diligence → Valuation → Transaction → Transfer → Servicing → Recovery
The debt purchase market can include both performing and non-performing receivables, depending on the transaction and seller’s strategy.
Debt Purchase and Debt Collection
Debt purchase and debt collection are separate activities.
A debt purchaser acquires the relevant debt or economic interest in a portfolio. A collection agency or servicer generally performs recovery activities for a creditor, debt owner, or purchaser.
A debt purchaser may therefore use:
- Internal collection teams
- External collection agencies
- Specialist servicers
- Legal recovery providers
- Digital collection platforms
- Other recovery partners
The ownership and servicing functions can be separated, allowing organizations to specialize in different parts of the debt lifecycle.
The Debt Purchase Market
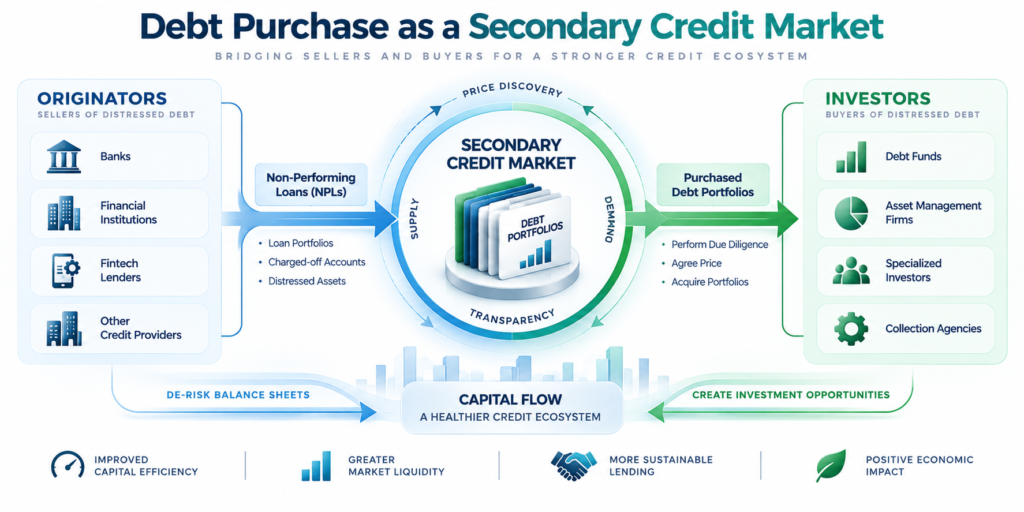
The debt purchase market creates a secondary market for credit exposures that lenders and other creditors may no longer wish to manage directly.
The market connects several stages of the credit lifecycle:
Originators → Debt Sellers → Debt Buyers → Servicers → Collection & Recovery → Portfolio Resolution
The market can support different strategic objectives for sellers and buyers.
For Debt Sellers
A portfolio sale can help a seller:
- Generate liquidity
- Reduce exposure to selected assets
- Transfer recovery responsibilities
- Manage distressed portfolios
- Reduce long-term servicing requirements
- Reallocate operational resources
- Simplify portfolio management
For Debt Buyers
A debt purchaser may seek to:
- Acquire portfolios below face value
- Generate returns from future recoveries
- Apply specialized servicing strategies
- Use portfolio analytics
- Improve recovery performance
- Build exposure to specific asset classes
- Develop recurring acquisition channels
The market is influenced by credit conditions, interest rates, economic activity, regulatory requirements, investor demand, lending volumes, recovery performance, and the availability of suitable portfolios.
Types of Debt Purchased
Debt purchase covers a broad range of assets. The characteristics of the underlying debt can significantly affect valuation, due diligence, transaction structure, and servicing requirements.
Consumer Debt
Consumer debt portfolios may include:
- Personal loans
- Credit cards
- Retail finance
- Consumer finance
- Buy-now-pay-later receivables
- Unsecured consumer credit
Consumer portfolios can contain large numbers of relatively small accounts, making data quality, segmentation, technology, and scalable servicing particularly important.
Commercial Debt
Commercial portfolios may include business loans, corporate receivables, commercial credit, and other business-related obligations.
These transactions may involve fewer accounts with larger balances and can require more detailed financial and legal analysis.
SME Debt
SME portfolios can sit between consumer and corporate debt in terms of account size and complexity.
Buyers may need to assess:
- Business financial information
- Guarantees
- Security
- Trading conditions
- Company structure
- Legal status
- Recovery history
Secured Debt
Secured debt is supported by collateral.
Examples include:
- Mortgages
- Vehicle finance
- Property-backed lending
- Asset-backed commercial loans
The valuation process may therefore consider both the debt and the expected value and timing of collateral realization.
Unsecured Debt
Unsecured debt does not have specific collateral supporting the obligation.
Recovery potential may depend more heavily on:
- Borrower information
- Contactability
- Payment behaviour
- Historical collections
- Legal enforceability
- Collection strategy
- Servicing performance
Non-Performing Debt
Non-performing debt represents exposures that have stopped performing according to the applicable contractual or regulatory criteria.
These portfolios are often evaluated using detailed recovery models because future cash flows can be uncertain.
How Debt Purchase Works
A debt purchase transaction typically moves through several stages.
1. Portfolio Selection
The seller identifies accounts that may be suitable for disposal.
Selection criteria may include:
- Delinquency status
- Product type
- Account balance
- Geography
- Borrower segment
- Historical recovery
- Legal status
- Security
- Internal portfolio strategy
The seller may create a portfolio containing similar accounts or combine several segments into a larger transaction.
2. Data Preparation
The seller prepares the information required by potential buyers.
A debt portfolio data file may contain:
- Account reference
- Original balance
- Current balance
- Principal outstanding
- Interest and fees
- Origination date
- Delinquency date
- Payment history
- Previous collection activity
- Customer information
- Contact details
- Legal status
- Security information
Data definitions should be clear and consistent so buyers can interpret the portfolio correctly.
3. Buyer Identification
The seller identifies suitable buyers based on:
- Asset class
- Geography
- Portfolio size
- Buyer capacity
- Servicing capability
- Investment strategy
- Regulatory requirements
Potential buyers may include specialist debt purchasers, credit funds, institutional investors, private equity firms, and other qualified investors.
4. Confidentiality and Data-Room Access
Before detailed portfolio information is shared, the parties may enter into confidentiality arrangements.
Qualified buyers can then receive access to a secure data room containing portfolio information and supporting documentation.
5. Due Diligence
The buyer analyses the portfolio from financial, legal, data, operational, and regulatory perspectives.
6. Valuation and Bidding
The buyer develops a valuation based on expected recoveries, costs, timing, and risk.
The buyer may then submit an indicative or final offer.
7. Negotiation and Documentation
The parties negotiate:
- Purchase price
- Payment terms
- Completion conditions
- Representations and warranties
- Data transfer
- Servicing arrangements
- Other transaction requirements
8. Closing and Transfer
Once conditions are satisfied, the transaction closes and the relevant debt interests and information are transferred according to the agreed structure.
9. Servicing and Recovery
The buyer or appointed servicer begins managing the portfolio.
Recovery strategies may include:
- Customer engagement
- Payment arrangements
- Settlements
- Digital collections
- Skip tracing
- Legal recovery
- Collateral realization where applicable
Debt Purchase Transaction Structures
Debt portfolios can be sold through different transaction structures depending on the seller’s objectives and the characteristics of the assets.
Bilateral Transactions
A seller negotiates directly with one potential buyer.
This approach can allow detailed negotiation around:
- Price
- Portfolio scope
- Transaction terms
- Representations
- Servicing
- Completion requirements
Competitive Portfolio Sales
A seller may approach multiple qualified buyers.
The process can involve:
Buyer Qualification → NDA → Data Room → Due Diligence → Indicative Bids → Shortlist → Final Bids → Negotiation → Closing
Competitive processes can provide sellers with multiple market indications while allowing buyers to evaluate the same portfolio information.
Forward-Flow Agreements
A forward-flow arrangement provides for recurring sales of qualifying debt portfolios over an agreed period.
Instead of completing a single transaction, the seller and buyer establish criteria for future portfolio transfers.
Forward-flow structures can be used where the seller expects a continuing flow of eligible receivables.
Key Participants in Debt Purchase
The debt purchase ecosystem involves several participants.
Debt Sellers
Debt sellers may include:
- Banks
- Financial institutions
- Consumer lenders
- Credit providers
- Finance companies
- Other debt owners
Debt Buyers
Debt buyers acquire portfolios and assume the relevant rights and economic exposure under the transaction structure.
Investors
Investment capital may come from:
- Institutional investors
- Credit funds
- Private equity firms
- Distressed-debt investors
- Specialist investment firms
Debt Servicers
Servicers manage the operational activities associated with purchased portfolios.
Their responsibilities may include:
- Account administration
- Customer communication
- Collections
- Payment processing
- Reporting
- Complaints management
- Legal coordination
Collection Agencies
Collection agencies may be appointed to perform specific recovery activities on behalf of debt owners or servicers.
Legal and Advisory Providers
Specialist legal, financial, tax, valuation, data, and transaction advisers may support complex portfolio transactions.
Debt Portfolio Valuation
Debt portfolio valuation determines the economic value of a portfolio to a potential buyer.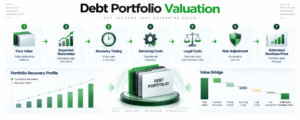
The outstanding balance is an important starting point, but it does not determine the purchase price.
A simplified valuation framework is:
Expected Recoveries − Servicing Costs − Legal Costs − Other Expenses = Expected Net Recoveries
The buyer then considers the timing and uncertainty of those cash flows.
Face Value
Face value or outstanding balance represents the amount owed under the accounts.
A portfolio with a large balance may still have limited acquisition value if expected recoveries are low.
Expected Recoveries
Buyers may assess:
- Historical collection performance
- Payment behaviour
- Delinquency age
- Borrower characteristics
- Contactability
- Legal status
- Collateral
- Comparable portfolios
Recovery Timing
The timing of future collections affects portfolio economics.
A recovery received earlier can have a different value from the same recovery received several years later.
Servicing Costs
Potential costs include:
- Collection fees
- Servicing fees
- Technology expenses
- Operational costs
- Skip-tracing expenses
- Legal support
Risk Adjustment
Buyers may adjust their valuation for uncertainty relating to:
- Data quality
- Legal enforceability
- Borrower behaviour
- Economic conditions
- Regulatory requirements
- Servicing performance
Debt Purchase Due Diligence
Due diligence provides buyers with a structured method of assessing portfolio quality before completing an acquisition.
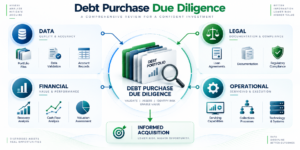
Data Due Diligence
Data review can examine:
- Account balances
- Account status
- Payment history
- Duplicate accounts
- Missing information
- Delinquency dates
- Customer details
- Portfolio segmentation
Legal Due Diligence
Legal analysis may cover:
- Original agreements
- Assignment rights
- Documentation
- Enforceability
- Limitation periods
- Litigation
- Insolvency
- Security interests
- Regulatory requirements
Financial Due Diligence
Financial analysis can include:
- Historical collections
- Recovery rates
- Outstanding balances
- Cash-flow performance
- Collection costs
- Settlement performance
- Recovery forecasts
Operational Due Diligence
Buyers should understand how the portfolio can be managed after acquisition.
This may involve assessing:
- Servicing capability
- Collection infrastructure
- Technology
- Customer communication
- Reporting
- Legal resources
- Compliance processes
Debt Purchase Data
Data is one of the most important assets in a debt portfolio transaction.
A buyer needs sufficient information to understand the portfolio and develop a realistic recovery model.
A useful portfolio data structure may include:
Data Area | Examples |
Account | Account ID, product type, status |
Balance | Principal, interest, fees, total balance |
Delinquency | Days past due, delinquency date |
Payments | Last payment, payment history |
Customer | Location, contact information |
Recovery | Previous collection activity |
Legal | Litigation, legal status |
Security | Collateral and security information |
The completeness and accuracy of this information can directly affect the buyer’s ability to assess the portfolio.
Buying a Debt Portfolio
A buyer should evaluate the portfolio beyond its headline balance.
Key questions include:
Portfolio Composition
What types of debt are included, and how concentrated is the portfolio?
Account Quality
How old are the accounts and what payment history is available?
Recovery Potential
What level of future recovery appears achievable based on available evidence?
Data Quality
Is sufficient information available to support segmentation and recovery?
Legal Position
Can the debt be transferred and enforced under the applicable legal framework?
Servicing Requirements
What operational capabilities are required to manage the accounts?
Investment Economics
Does the expected recovery profile support the proposed acquisition price and associated costs?
Scenario analysis can help buyers assess how different recovery levels and timing assumptions affect the investment model.
Selling a Debt Portfolio
Preparing a portfolio properly can help sellers create a more efficient transaction process.
A seller should consider:
- Defining the portfolio clearly
- Validating account balances
- Reviewing documentation
- Organizing payment history
- Preparing standardized data
- Identifying legal matters
- Confirming security information
- Establishing a secure data room
A seller may also need to determine whether the transaction will be bilateral, competitive, or structured as a forward flow.
Clear portfolio information can help potential buyers complete due diligence and develop more informed bids.
Debt Purchase Agreements and Transfer
The legal documentation supporting a transaction establishes the framework for the transfer.
Depending on the transaction, agreements may address:
- Assets being transferred
- Purchase price
- Payment terms
- Completion conditions
- Representations and warranties
- Data transfer
- Confidentiality
- Servicing
- Liability
- Regulatory obligations
- Post-completion responsibilities
The precise requirements depend on the jurisdiction, asset class, transaction structure, and applicable regulations.
Legal and regulatory review is particularly important where portfolios contain consumer debt, cross-border assets, secured loans, or accounts subject to existing legal proceedings.
Debt Servicing After Acquisition
Acquiring a portfolio creates an ongoing servicing requirement.
The buyer may establish an internal servicing operation or appoint a third-party servicer.
Typical activities include:
- Account administration
- Customer communication
- Payment processing
- Collections
- Settlement management
- Complaints handling
- Legal coordination
- Performance reporting
Portfolio Segmentation
Accounts can be segmented based on:
- Balance
- Delinquency age
- Loan type
- Geography
- Contactability
- Payment history
- Legal status
- Security
- Previous recovery activity
Segmentation allows servicing strategies to be aligned with portfolio characteristics.
Performance Monitoring
Buyers and servicers may monitor:
- Gross collections
- Net collections
- Recovery rate
- Cost-to-collect
- Cash collected versus forecast
- Settlement performance
- Payment-plan performance
- Legal recovery
- Servicing costs
This helps identify differences between actual portfolio performance and the assumptions used during acquisition.
Technology in Debt Purchase
Technology supports almost every stage of the debt purchase lifecycle.
Portfolio Analytics
Analytics can help identify:
- Balance concentration
- Delinquency patterns
- Recovery trends
- Geographic distribution
- Customer segments
- Account-level performance
Artificial Intelligence and Machine Learning
AI and machine learning can support:
- Recovery forecasting
- Customer segmentation
- Payment propensity modelling
- Contact strategy
- Collection prioritization
- Communication timing
Digital Servicing
Digital channels can support:
- Customer self-service
- Online payments
- Automated communication
- Payment-plan management
- Account information
- Reporting
Technology can improve scalability and analytical capability while operating within applicable compliance and customer-protection requirements.
Risks in Debt Purchase
Debt purchase involves uncertainty that should be incorporated into portfolio analysis and transaction planning.
Recovery Risk
Actual recoveries can differ from projections.
Data Risk
Incomplete or inaccurate information can affect valuation and recovery strategies.
Legal Risk
Debt enforceability, assignment requirements, limitation periods, and legal processes can vary by jurisdiction.
Servicing Risk
Portfolio performance can be affected by operational capability, collection strategy, technology, and execution.
Regulatory Risk
Debt transactions and subsequent recovery activities can be subject to regulations covering consumer protection, privacy, licensing, financial services, and debt collection.
Economic Risk
Changes in employment, inflation, interest rates, property values, and business conditions can influence borrower repayment capacity.
Timing Risk
Recoveries can take longer than expected, affecting cash-flow forecasts and investment economics.
Debt Purchase Market Trends
The debt purchase market continues to develop alongside changes in lending, technology, regulation, and investment strategies.
Data-Driven Transactions
Buyers increasingly rely on detailed portfolio data and analytics when assessing acquisition opportunities.
Data quality can influence both due diligence and pricing.
Digital Recovery
Digital communication and payment channels are increasingly integrated into portfolio servicing.
These can include:
- SMS
- Online payment portals
- Mobile applications
- Messaging platforms
- Digital payment systems
AI-Powered Portfolio Analysis
AI and advanced analytics can help participants process large volumes of account information and identify patterns in recovery performance.
Specialist Debt Buyers
Buyers may increasingly focus on particular asset classes, jurisdictions, borrower segments, or delinquency stages.
Regulatory Focus
Consumer protection, data privacy, debt collection, licensing, insolvency, and debt-sale requirements remain important considerations when structuring and servicing debt portfolios.
Debt Purchase vs Other Debt Strategies
Debt purchase is one of several ways a creditor can manage outstanding debt.
Strategy | Ownership | Typical Objective |
Internal Collections | Retained by creditor | Recover internally |
Outsourced Collections | Retained by creditor | Use external recovery expertise |
Restructuring | Retained by creditor | Modify repayment terms |
Debt Sale | Transferred to buyer | Transfer ownership/economic exposure |
Forward Flow | Recurring transfer | Establish ongoing portfolio disposal |
Legal Recovery | Depends on structure | Pursue formal recovery |
The appropriate strategy depends on the creditor’s objectives, portfolio characteristics, regulatory environment, operational capability, and expected economics.
Debt Purchase Transaction Checklist
For Sellers
Portfolio
- Define the assets being offered.
- Validate balances and account status.
- Review portfolio segmentation.
Data
- Prepare accurate portfolio data.
- Document data definitions.
- Identify missing information.
Documentation
- Review loan agreements.
- Confirm assignment rights.
- Identify legal matters.
- Review security information.
Transaction
- Identify suitable buyers.
- Establish confidentiality arrangements.
- Prepare the data room.
- Evaluate bids.
- Negotiate transaction terms.
For Buyers
Portfolio
- Understand the asset composition.
- Analyse account-level characteristics.
- Review concentration and segmentation.
Data
- Validate portfolio information.
- Assess completeness.
- Review historical performance.
Legal
- Review enforceability.
- Confirm transfer requirements.
- Identify litigation and regulatory issues.
Financial
- Model expected recoveries.
- Estimate costs.
- Consider recovery timing.
- Test multiple scenarios.
Operations
- Establish servicing requirements.
- Assess technology.
- Plan customer communication.
- Determine legal and recovery resources.