Portfolio sales are a central part of the secondary debt market, allowing lenders, financial institutions, businesses, and investors to transfer groups of credit assets to new owners.
Rather than selling individual accounts one at a time, a portfolio sale brings multiple receivables, loans or other debt exposures together into a structured transaction. The portfolio may contain performing accounts, delinquent receivables, non-performing loans, distressed debt or a combination of asset types, depending on the seller’s objectives and the buyer’s investment strategy.
A portfolio sale is therefore more than a transaction based on an outstanding balance. Buyers need to understand the composition, performance, documentation, legal position, servicing requirements and expected future cash flows of the assets. Sellers, meanwhile, need to prepare the portfolio so that potential buyers can conduct meaningful due diligence and establish an appropriate valuation.
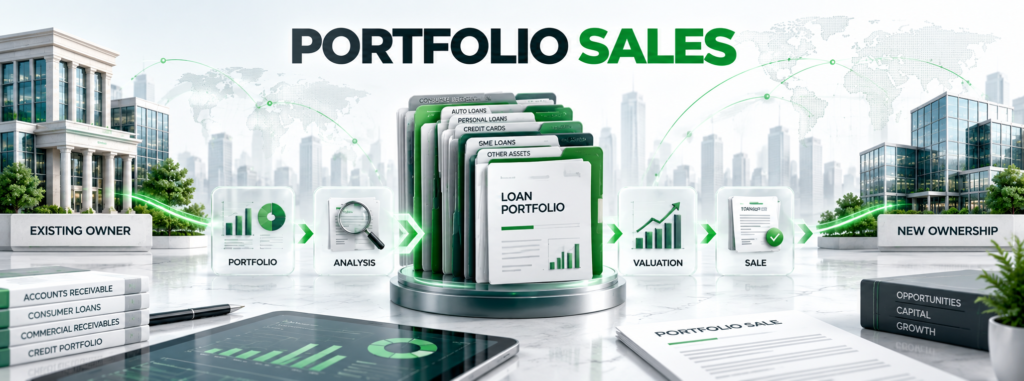
The process typically moves through:
Portfolio Identification → Data Preparation → Buyer Selection → Due Diligence → Valuation → Bidding → Negotiation → Transaction → Transfer → Servicing
This lifecycle connects portfolio owners with debt buyers, institutional investors, investment funds and specialist servicing providers.
For participants in the debt sale and purchase market, understanding how portfolio sales are structured is essential to evaluating opportunities, preparing assets for market and managing transactions from initial preparation through post-sale servicing.
What Is a Portfolio Sale?
A portfolio sale is the transfer or sale of a group of financial assets from one owner to another.
The assets can include:
- Consumer receivables
- Commercial receivables
- Loan portfolios
- Credit card receivables
- Non-performing loans
- Distressed debt
- Utility receivables
- Telecommunications receivables
- Unsecured debt
- Secured debt
- Other contractual payment obligations
The exact structure depends on the type of assets, the rights being transferred, applicable contracts and the legal and regulatory framework.
A portfolio sale may involve thousands of individual accounts, each with its own balance, payment history and documentation.
This creates a fundamental distinction between portfolio size and portfolio value.
A portfolio with a large face value is not necessarily worth more than a smaller portfolio. Buyers assess expected cash flows, recovery potential, timing, costs, risks and the quality of the underlying information before determining what they are prepared to pay.
Why Do Portfolio Sales Occur?
A portfolio owner may decide to sell assets for a range of strategic, financial or operational reasons.
Balance-Sheet Management
An organisation may want to reduce exposure to particular credit assets or adjust the composition of its balance sheet.
Portfolio Rebalancing
A seller may decide that certain assets no longer fit its current investment or lending strategy.
Liquidity
Selling a portfolio can convert existing credit assets into immediate transaction proceeds, subject to the agreed structure and pricing.
Risk Management
A portfolio sale can change exposure to particular borrowers, products, sectors, geographies or credit-risk categories.
Operational Focus
Managing a large or specialised portfolio requires servicing, collections, technology and reporting resources. A sale may allow the owner to focus on other areas of its business.
Strategic Portfolio Management
Financial institutions and investment managers may periodically review their holdings and determine whether certain assets should remain in the portfolio.
The reason for a sale can influence how the portfolio is prepared, priced and presented to potential buyers.
Types of Portfolios Sold
Portfolio sales can involve different asset classes and performance stages.
Performing Portfolios
Performing portfolios generally contain accounts where payments are being made according to the expected schedule.
Buyers may focus on:
- Payment history
- Remaining maturity
- Cash-flow stability
- Credit quality
- Yield
- Concentration
- Documentation
Delinquent Portfolios
Delinquent portfolios contain accounts where payments are overdue.
The degree of delinquency can vary significantly, making segmentation particularly important.
Non-Performing Portfolios
Non-performing portfolios contain accounts with significant payment problems.
Valuation may depend heavily on:
- Historical collections
- Expected recoveries
- Recovery timing
- Servicing capability
- Legal position
- Documentation
- Collection costs
Distressed Portfolios
Distressed portfolios may contain credit exposures where the underlying borrower or debtor is experiencing significant financial difficulty.
These transactions can require more extensive legal, financial and recovery analysis.
Portfolio Sales Lifecycle
A successful portfolio sale requires coordination across multiple stages.
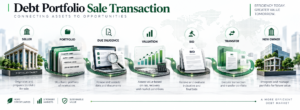
Portfolio Identification
The seller determines which assets may be suitable for sale.
Data Preparation
Account-level information is collected, cleaned, validated and organised.
Buyer Identification
Potential buyers are identified according to portfolio characteristics.
Due Diligence
Buyers examine the available data, documentation, performance and legal position.
Valuation
Potential buyers estimate the economic value of the portfolio.
Bidding
Qualified buyers may submit offers according to the transaction process.
Negotiation
The seller and selected buyer negotiate price and contractual terms.
Transaction and Closing
The transaction is documented and completed.
Transfer
The relevant ownership or contractual rights move to the buyer.
Servicing
The portfolio continues to be administered, collected and monitored.
This process means that portfolio sales require both financial analysis and transaction management.
Preparing a Portfolio for Sale
Portfolio preparation is one of the most important stages of the transaction.
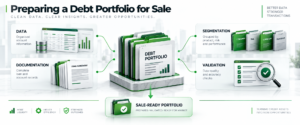
A buyer needs enough information to understand the assets and develop a valuation.
The seller may need to organise:
- Account-level data
- Outstanding balances
- Payment histories
- Delinquency status
- Customer information
- Product information
- Contractual documentation
- Security information
- Legal information
- Collection history
- Recovery history
- Servicing information
Data Cleaning
Data should be reviewed for inconsistencies, duplicates, missing information and balance discrepancies.
Data Standardisation
A consistent data structure makes it easier for buyers to analyse the portfolio.
Portfolio Segmentation
The seller may divide the portfolio into meaningful groups based on factors such as:
- Product
- Geography
- Balance
- Age
- Delinquency
- Customer type
- Payment behaviour
Documentation Review
Supporting documentation should be identified and organised so buyers can understand the underlying contractual rights.
A well-prepared portfolio can make due diligence more efficient and provide buyers with greater visibility into the assets.
Portfolio Data and the Data Tape
The portfolio data tape is one of the most important components of a debt portfolio transaction.
It provides structured information about the individual accounts within the portfolio.
Depending on the asset type, a data tape may contain:
Category | Examples |
|---|---|
Account | Account reference, product |
Balance | Principal, interest, fees |
Payment | Amounts, dates, history |
Delinquency | Days past due, status |
Contract | Agreement, maturity |
Customer | Relevant borrower information |
Collection | Actions and outcomes |
Legal | Disputes, proceedings |
Recovery | Historical recoveries |
Servicing | Current servicing information |
The quality of the data tape directly affects a buyer’s ability to assess the portfolio.
A buyer may compare the data tape against supporting records and sample accounts during due diligence.
Portfolio Due Diligence
Due diligence allows potential buyers to verify the information provided by the seller and assess the risks associated with the portfolio.
Data Due Diligence
Buyers may test:
- Data completeness
- Balance accuracy
- Account counts
- Duplicate records
- Payment history
- Delinquency status
- Historical performance
Financial Due Diligence
Financial analysis may examine:
- Historical collections
- Recovery performance
- Expected cash flows
- Portfolio composition
- Collection costs
- Account-level performance
Legal Due Diligence
Legal review may consider:
- Ownership
- Contractual rights
- Assignment provisions
- Security
- Guarantees
- Enforcement rights
- Documentation
- Transfer restrictions
Operational Due Diligence
Operational analysis can cover:
- Current servicer
- Collection processes
- Technology
- Reporting
- Customer communication
- Recovery processes
Due diligence gives buyers the information required to move from a portfolio description to an investment assessment.
Portfolio Valuation
Portfolio valuation is at the centre of the sales process.
The face value of the portfolio provides an important starting point, but it does not determine the transaction price.
A simplified valuation framework is:
Face Value → Expected Cash Flows → Timing → Costs → Risk → Estimated Value → Purchase Price
Face Value
The total contractual amount outstanding across the portfolio.
Expected Cash Flows
The buyer estimates how much money may actually be collected.
Timing
The expected timing of collections affects their economic value.
Costs
Servicing, collection, legal and recovery costs can reduce net cash flows.
Risk
Uncertainty around payment behaviour, documentation, enforceability and recoveries can influence pricing.
Purchase Price
The buyer ultimately determines how much it is prepared to pay based on its own investment assumptions and required economics.
This is why two buyers can assess the same portfolio differently.
Portfolio Pricing Factors
A buyer may consider multiple variables when developing a bid.
Portfolio Composition
Different asset types can have different risk and recovery characteristics.
Payment Performance
Historical payment behaviour can provide insight into expected future collections.
Delinquency
The age and severity of delinquency can influence recovery expectations.
Recovery History
Historical recoveries can help buyers assess potential future performance.
Documentation
The completeness and quality of underlying documentation can affect enforceability and transaction risk.
Servicing
The existing servicing infrastructure can influence the cost and effectiveness of future collections.
Concentration
High exposure to particular borrowers, products or geographic areas can introduce concentration risk.
Legal Position
Potential legal restrictions, disputes or enforcement issues can affect valuation.
Buyer Identification and Portfolio Marketing
Not every portfolio is suitable for every buyer.
A seller should consider the characteristics of the portfolio when identifying potential purchasers.
Potential buyers may include:
- Debt purchasers
- Investment funds
- Private credit investors
- Banks
- Institutional investors
- Specialist finance companies
- Distressed-debt investors
- Other eligible market participants
Buyer selection can be influenced by:
- Asset class
- Geography
- Portfolio size
- Credit quality
- Expected recovery
- Investment strategy
- Servicing requirements
- Regulatory considerations
A well-defined buyer universe can make the transaction process more focused and efficient.
Portfolio Bidding
Once qualified buyers have reviewed the available information, the transaction may move into a bidding stage.
A bidding process can be structured in different ways.
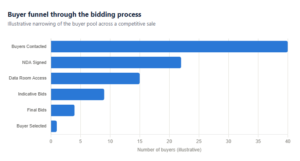
Indicative Bids
Potential buyers provide an initial indication of the price they may be willing to pay.
Detailed Due Diligence
Selected buyers receive additional information for deeper analysis.
Final Bids
Buyers submit more developed offers based on their due-diligence findings.
Selection
The seller evaluates the bids according to the transaction requirements.
Price is an important component, but transaction terms, execution requirements, representations, conditions and servicing arrangements can also influence the final structure.
Negotiating a Portfolio Sale
Once a preferred buyer has been identified, the parties may negotiate the transaction documentation.
Important areas can include:
- Purchase price
- Closing conditions
- Transfer mechanics
- Representations
- Warranties
- Indemnities
- Eligibility criteria
- Data requirements
- Servicing arrangements
- Payment terms
- Post-closing obligations
The final agreement defines the rights and responsibilities of the parties.
The specific provisions depend on the asset type, transaction structure and applicable legal framework.
Portfolio Transfer
Transfer is the point at which the relevant rights associated with the portfolio move from the seller to the buyer according to the transaction agreement.
The process may involve:
- Transfer documentation
- Account-level records
- Contractual assignments
- Security documentation
- Data transfer
- Servicing instructions
- Payment account changes
- Reconciliation
A controlled transfer process is important because even a well-valued portfolio can experience operational problems if account data, documentation or servicing information is transferred incorrectly.
Servicing After Portfolio Sale
The transaction does not end when ownership changes.
The portfolio still requires ongoing management.
The servicer may be responsible for:
- Payment processing
- Customer communication
- Collections
- Account administration
- Reconciliation
- Reporting
- Recovery
- Compliance processes
The existing servicer may remain in place, or the buyer may appoint a new provider.
Servicing Transition
If servicing changes, the transition can require:
Data Mapping → System Testing → Account Validation → Communication Setup → Operational Handover → Performance Monitoring
The quality of this transition can influence the post-acquisition performance of the portfolio.
Portfolio Sales and the Secondary Debt Market
Portfolio sales are a fundamental mechanism of the secondary debt market.
They allow existing credit assets to move between owners rather than remaining permanently with the original creditor.
A simplified secondary-market structure is:
Originator → Portfolio → Seller → Buyer → New Owner → Servicer → Recovery / Repayment
This creates opportunities for different market participants to pursue different strategies.
A bank may sell a portfolio that no longer fits its balance-sheet objectives.
An investment fund may acquire the portfolio based on its expected cash flows.
A specialist servicer may manage the accounts on behalf of the new owner.
Another investor may later acquire the portfolio through a subsequent transaction.
The same underlying debt can therefore move through several ownership and servicing stages during its lifecycle.
Portfolio Sales and Portfolio Performance
Portfolio performance does not stop being relevant after a sale.
The buyer may establish ongoing performance monitoring to compare actual results with the assumptions used during acquisition.
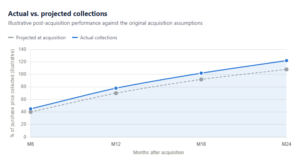
Important indicators can include:
- Collections
- Recoveries
- Delinquency movement
- Resolution rates
- Cost to collect
- Cash-flow timing
- Servicing performance
- Portfolio yield
This information can be used to update valuations and inform future portfolio decisions.
For example, stronger-than-expected collections may change the buyer’s assessment of remaining assets, while weaker performance may lead to changes in servicing strategy.
Technology in Portfolio Sales
Technology increasingly supports the preparation, analysis and management of debt portfolio transactions.
Digital systems can support:
- Data validation
- Portfolio segmentation
- Data-room management
- Buyer analysis
- Valuation models
- Due-diligence workflows
- Transaction management
- Servicing
- Performance reporting
Technology is particularly valuable when portfolios contain large numbers of accounts.
Instead of treating every account as an isolated record, structured data allows buyers and sellers to analyse portfolio-level patterns.
This can improve the visibility of:
- Payment behaviour
- Delinquency
- Recovery trends
- Concentration
- Account segmentation
- Expected cash flows
Portfolio Sales Risk Factors
Portfolio transactions involve several categories of risk.
Data Risk
Incorrect, incomplete or inconsistent information can affect valuation and due diligence.
Documentation Risk
Missing or incomplete documentation can create uncertainty around contractual rights.
Valuation Risk
Actual collections may differ from the assumptions used to determine the purchase price.
Legal Risk
Transferability, enforceability and regulatory requirements can vary by asset and jurisdiction.
Servicing Risk
Collection and administration performance can affect post-acquisition results.
Concentration Risk
A portfolio may have significant exposure to particular borrowers, products, industries or locations.
Timing Risk
Recoveries may take longer than expected, affecting cash-flow assumptions.
Portfolio buyers therefore need to evaluate both the assets themselves and the infrastructure supporting those assets.
What Makes a Portfolio Attractive to Buyers?
There is no single characteristic that determines the attractiveness of a portfolio.
Potential buyers may consider a combination of:
Data Quality
Can the portfolio be analysed efficiently?
Performance History
What has happened to the accounts historically?
Recovery Potential
What future collections may be achievable?
Documentation
Are the relevant contractual records available?
Servicing
Can the portfolio be efficiently managed after acquisition?
Diversification
Is the portfolio sufficiently diversified across relevant categories?
Pricing
Does the purchase price align with the buyer’s assumptions and investment strategy?
Transferability
Can the relevant rights be transferred under the applicable arrangements?
The interaction between these factors determines how a buyer may assess the opportunity.
Portfolio Sales: Seller and Buyer Perspectives
The same portfolio can be viewed differently by the seller and buyer.
Seller Perspective
The seller may focus on:
- Portfolio value
- Execution certainty
- Timing
- Risk transfer
- Operational efficiency
- Strategic objectives
Buyer Perspective
The buyer may focus on:
- Expected cash flows
- Purchase price
- Recovery potential
- Data quality
- Documentation
- Servicing costs
- Downside scenarios
- Exit opportunities
The transaction brings these perspectives together through due diligence, valuation and negotiation.